logo solution aide prêt hypothécaire
Mortgage

Buying a property as a non-resident in Belgium

Are you thinking of buying a house or flat in the Province of Luxembourg to live in?

Whether you are  a Luxembourg cross-border worker, a Luxembourg resident or a French resident, it is essential to fully understand the rules governing the granting of a mortgage for the purchase of a property with a view to establishing your main residence in Belgium. As a mortgage broker based in Belgium with a branch in Luxembourg, Clicredit supports you throughout the process to help you make the right financial choices. We recognise the importance of this significant step; that is why our team takes the time to analyse your application and compare borrowing options tailored to your situation.

👉 If you wish to buy a property in Belgium with a view to letting it out, you must already be a resident of Belgium.

Who can take out a mortgage to buy a property in Belgium to live in?

To be eligible for a mortgage as a first-time buyer who is not a resident of Belgium, you must be:

  • A natural person

    Not a legal entity

  • Resident in Belgium within three months of purchasing the property

  • Be aged 75 or under at the end of the loan term

    (80 years of age if the loan-to-value ratio is less than 80 per cent) and at least 18 years of age when the contract is signed

  • Acting primarily in a private capacity

    less than 50% for business purposes

What projects are eligible for financing?

You can borrow to:
⚠️ Self-build projects (where you carry out the work yourself) are not eligible.

How much can you borrow?

Pictogramme montant du crédit Belgique
Amount: between €25,000 and €1,000,000
Pictogramme durée du crédit Belgique
Term: from 8 to 30 years
Pictogramme remboursement du crédit Belgique
Repayment: fixed or decreasing monthly instalments
Pictogramme quotité du crédit Belgique
Maximum loan-to-value ratio: up to 90 per cent of the property’s value

💡 Purchase costs (registration fees, notary fees, VAT, etc.) must be covered by your own funds.

Your borrowing capacity: how is it assessed?

Your financial capacity depends on:

  • The expenses-to-income ratio
  • The minimum amount you need to retain after deducting your monthly repayments and current outgoings
  • Your family situation (single or in a couple, dependent children, outstanding loans, etc.) and job security


If you are approaching retirement age, an income weighting is applied (e.g. 70 per cent of net income for employees aged over 67) or based on mypension (for a Belgian pension) or the CNAP document (Luxembourgish pension).

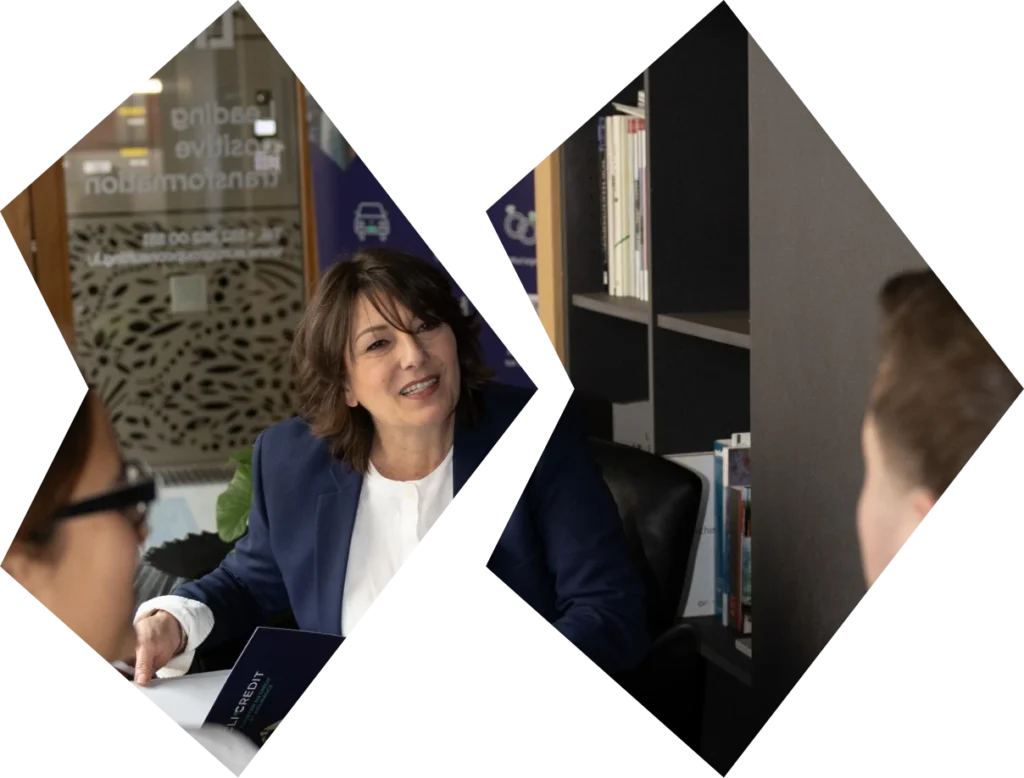
Trois personnes lors d'un rendez-vous de conseil autour d'un crédit ou un prêt à tempérament au Luxembourg. Une conseillère fait face à un couple.

Borrowing in the Province of Luxembourg: regional specifics

The Province of Luxembourg is attracting more and more Luxembourg residents because of its more affordable property prices.
However, please note that the eligibility criteria may vary depending on your place of residence and type of income.

Criteria Belgian resident Luxembourg or French resident (cross-border worker)

Residence in Belgium required

Yes

Yes, obligation to establish residence within 3 months of signing the deed of sale

Accepted sources of income

Employees, self-employed persons, pensioners, replacement income, rental income from a property in Belgium

Employees only (income in €), income from self-employed persons carrying out an activity in the Grand Duchy of Luxembourg, France or the Netherlands

Maximum loan-to-value ratio

Up to 100 per cent (125 per cent subject to strict conditions)

Limited to 90 per cent

Personal contribution

Mandatory for purchase-related costs (registration fees, deed fees, professional fees, administration charges, etc.) + 10% contribution in certain cases

Mandatory for purchase-related costs (registration fees, deed fees, professional fees, administration charges, etc.) + 10 per cent contribution in certain cases

Type of contract required

Permanent contract (CDI) of ≥ 6 months or proven job stability

Stable permanent contract required (no fixed-term or temporary contracts)

Income in foreign currency accepted

❌ Not accepted

❌ Not accepted

The role of the Energy Performance Certificate (EPC)

  • If the property’s PEB is > 700 kWh/m² per year

    A budget of at least €40,000 for energy-efficiency work may be required.

  • Eligible works

    Insulation, glazing, boilers, solar panels, ventilation, etc.

👉 Objective: to encourage energy-efficiency renovations for more energy-efficient homes.

Guarantees and release of funds

  • First-ranking mortgage on the property being financed

  • The property must be worth at least €125,000 before works begin

    Insulation, glazing, boiler, solar panels, ventilation, etc.

  • In the case of building works or new construction

    Funds released on the basis of invoices or signed purchase orders

Need some guidance?

At Clicredit, we can help you:

  • Calculate your borrowing capacity
  • Put together a strong application (for Belgian residents or cross-border workers)
  • Compare the best mortgage solutions


📞 Contact us at +3263245151 for a free, no-obligation simulation!

Request information about a mortgage

Our team communicates in 🇫🇷 – 🇱🇺 – 🇩🇪 – 🇬🇧 – 🇵🇹 – 🇮🇹

Contact details

Enquiry

Clicredit Luxembourg

Clicredit Luxembourg is a broker specialising in consumer credit and mortgage loans.

Our team has specialised in instalment loans for many years. This experience guarantees you a professional, high-quality service. As a credit broker, we compare the rates and offers from the various lenders and banks we work with to ensure you receive a financial solution tailored to your mortgage needs.